
Zacua Ventures Closes $135M Fund II for Physical Industries
TL;DR
San Francisco-based Zacua Ventures has closed its second fund at $135 million, more than double its $56 million debut fund from 2024, after coming in 35% oversubscribed. Fund II keeps backing early-stage companies across what the firm calls Physical Industries, construction, infrastructure, manufacturing, energy, mining, and housing, with a particular focus on physical AI, robotics, and alternative materials. The fund's LP base reads like a who's-who of the sectors it invests in, with Volvo Group, Holcim, Hilti, Trimble, and Acciona all named as backers alongside institutional investors like the Dubai Future District Fund.
Key Takeaways
The 35% oversubscription on a fund that's 2.4x the size of Fund I is a strong signal for a thesis many VCs still consider niche. Construction and heavy-industry tech has historically struggled to attract traditional venture capital, which tends to gravitate toward software-only businesses with faster, cleaner exit paths.
Corporate LPs are also customers and potential acquirers, which cuts both ways. Trimble is a limited partner in Fund II and is also the company that acquired Zacua's portfolio company Document Crunch, Fund I's headline exit. That overlap can accelerate exits and validate the thesis, but it also means some of Zacua's most important strategic relationships sit on both sides of the table.
"Physical AI" is becoming the organizing idea for an entire category of industrial venture investing. Zacua's Fund II thesis leans on the idea that AI and robotics are now mature enough to tackle physical, not just digital, industries, a framing that is showing up across a growing number of specialist funds this year.
A $200 million SoftBank-backed valuation for Gravis Robotics gives the firm a genuine marquee name. Among Fund I's investments, Gravis Robotics reaching a reported $1 billion valuation on a $200 million raise from SoftBank is the kind of outcome that makes the rest of a portfolio easier to raise against.
Fund Overview
Fund Name: Zacua Ventures Fund II
Fund Size: $135 million, closed 35% oversubscribed
Stage: Early-stage (pre-seed through Series A, based on Fund I pattern)
Geography: Global, with more than half of investments historically in North America; network spans Europe, Latin America, Asia, and the Middle East
Focus: Physical Industries, including construction, infrastructure, manufacturing, energy, mining, and housing, with emphasis on physical AI, robotics, and alternative materials
Key LPs: Volvo Group Venture Capital, Holcim Maqer Ventures, Hilti Venture, Trimble Ventures, Acciona, DPR Construction, Mortenson, and Dubai Future District Fund, among more than 30 total LPs across 20+ countries
Why This Fund Matters
Construction and heavy industry are enormous markets that have been chronically underserved by venture capital, mostly because the sales cycles are long, the customers are conservative, and the exits have historically run through strategic acquisition rather than IPO. Zacua's bet, and the bet of the roughly 30 corporates that backed Fund II, is that AI and robotics have finally reached the point where they can meaningfully change the economics of building, maintaining, and operating physical infrastructure.
The firm's LP list is itself the story here almost as much as the fund size. When Volvo, Holcim, Hilti, Trimble, and Acciona all write checks into the same early-stage fund, they are not just allocating capital; they are building a pipeline of potential partners, pilot customers, and acquisition targets for their own businesses. That is standard practice in corporate venture, but the concentration of major names from across construction equipment, building materials, power tools, and survey technology in one fund says something about how seriously the sector now takes software and robotics as a competitive threat, or opportunity, rather than a side bet.
The step-up from a $56 million debut fund to $135 million, a 2.4x increase, is a meaningful jump for a second fund, especially in a venture market where plenty of established managers have struggled to raise flat funds, let alone grow them. That the raise closed 35% oversubscribed suggests demand outstripped even an ambitious target, likely helped by Fund I's track record: 34 investments across 11 markets, all still operating, plus the Document Crunch exit and the Gravis Robotics valuation jump.
The risk in this category is less about deal flow and more about time horizons. Physical-industry startups often need more capital and more time to reach meaningful revenue than software companies, which puts pressure on a fund's ability to support portfolio companies through multiple rounds. Zacua's corporate LP base may help here, since corporates are frequently willing co-investors in later rounds for companies that fit their strategic interests, but that is a different kind of capital discipline than a purely financial LP base would impose.
The Team
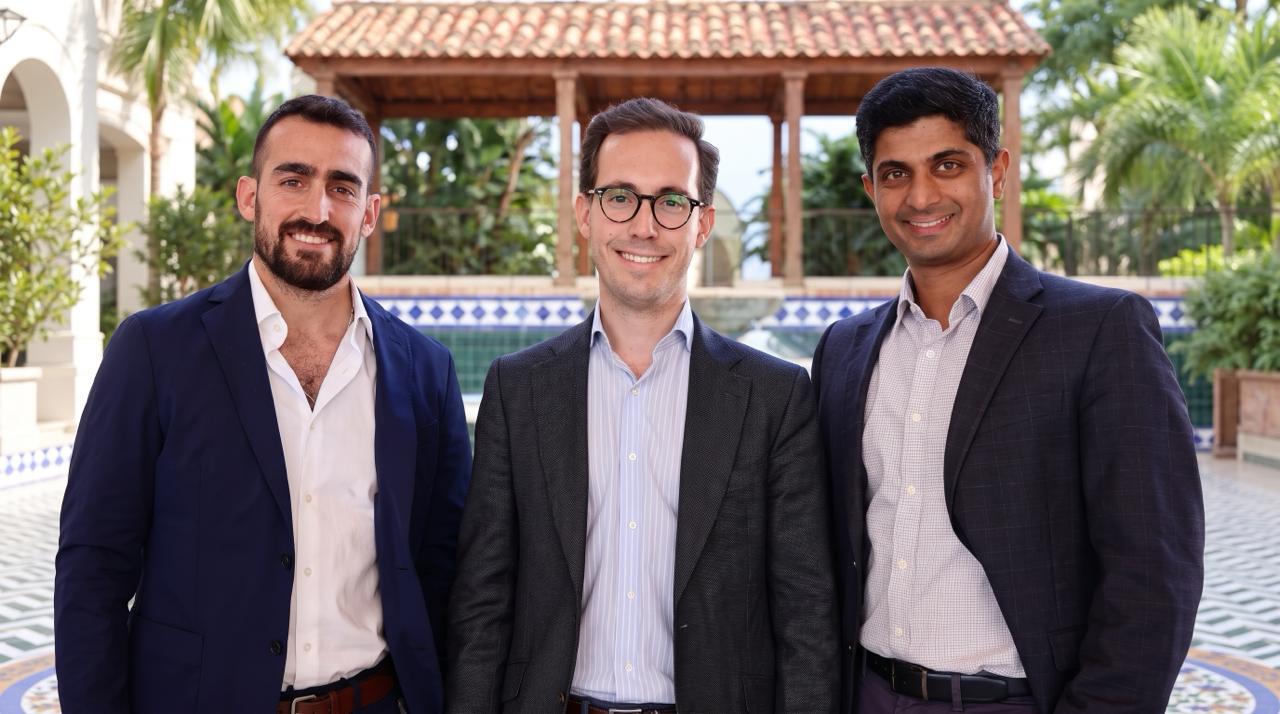
Zacua's Fund II announcement names three founding partners: Vivin Hegde, based in New York and San Francisco and covering North America; Juan Nieto, based in Madrid and covering Europe and Asia-Pacific; and Mauricio Tessi Weiss. The firm's own team page lists Hegde and Nieto as Founding Partners alongside a broader team that includes Margarita de la Peña as principal for North America and Latin America, Jun S Hibbard as partner for Japan, Anas Bataw as partner for the Middle East, and Philip Sondhu as partner for Australia and New Zealand. Current public materials do not clarify Mauricio Tessi Weiss's specific regional role within that structure.
Early Portfolio
Fund I's headline exit is Document Crunch, a construction-contract software company acquired by Trimble, which is both a Zacua portfolio company's acquirer and a Fund II limited partner. Gravis Robotics, also a Fund I investment, has reportedly raised $200 million from SoftBank at a $1 billion valuation. Fund II's early investments include Origin Robotics, CURA Climate, and Neuron Factory, though further detail on what each company does has not been disclosed in current coverage.
What This Means for Founders
Founders building in construction tech, industrial robotics, mining technology, or alternative building materials now have a fund with $135 million in fresh capital and, perhaps more valuably, direct access to a roster of corporate LPs who are also potential pilot customers. A founder pitching a jobsite robotics product, for instance, is pitching a fund whose LP base includes some of the largest construction and equipment companies in the world.
That same corporate-heavy LP base is worth weighing carefully. Founders should ask directly how Zacua manages potential conflicts when a portfolio company's natural acquirer, or competitor, sits on the fund's cap table, and should go in with eyes open about whether a given corporate LP's interest in their category might eventually shape exit options more than a pure financial sponsor would.
Fund Momentum Take
This is a genuinely interesting fund because the thesis and the capital structure reinforce each other in a way that's unusual outside of tightly focused corporate venture arms. Most generalist VCs that dabble in construction or industrial tech do it opportunistically; Zacua has built an entire LP base and investment thesis around physical industries, and the 35% oversubscription suggests the corporate world agrees there's a real opportunity here.
The thing we'd flag, not as a red flag but as a genuine structural question, is the Trimble relationship. Having your Fund I's best exit also be a current Fund II LP is a good outcome in isolation, since it proves the thesis works and keeps a strategically aligned investor close. But it also means Zacua's incentives around future deals in contract-management software, Document Crunch's category, now run through a relationship with the company that already bought the category leader. That is worth founders and co-investors understanding clearly rather than glossing over.
Our bet: physical AI and industrial robotics will keep attracting specialist capital through 2027, and funds with genuine corporate-LP distribution like Zacua's will have a real edge in sourcing and exits over purely financial competitors chasing the same thesis from the outside.
Frequently Asked Questions
What does Zacua Ventures invest in?
Early-stage companies across what the firm calls Physical Industries: construction, infrastructure, manufacturing, energy, mining, and housing, with an emphasis on physical AI, robotics, and alternative materials.
How big is Fund II compared to Fund I?
Fund II closed at $135 million, more than double Fund I's $56 million, and closed 35% oversubscribed.
Who are Zacua's limited partners?
More than 30 corporate and institutional investors across 20+ countries, including named backers Volvo Group, Holcim, Hilti, Trimble, Acciona, DPR Construction, Mortenson, and the Dubai Future District Fund.
Who runs the fund?
Founding partners Vivin Hegde (North America), Juan Nieto (Europe and Asia-Pacific), and Mauricio Tessi Weiss, supported by a team covering Latin America, Japan, the Middle East, and Australia/New Zealand.
What has Zacua's Fund I produced so far?
34 investments across 11 markets, all still operating as of the announcement, including the acquisition of Document Crunch by Trimble and a reported $1 billion valuation for Gravis Robotics after a $200 million SoftBank-backed raise.
Have a fund closing to announce? Submit your fund here.
Need help raising capital? Check out our Fundraising Advisory services.
Related funds in the index
PropTech funds from the verified index
| Fund | Size | Stage | Location | Focus |
|---|---|---|---|---|
| Curiosity VC Fund II | €17M EUR | Pre Seed | Netherlands | AI/ML, PropTech +6 |
| Base10 Series B Fund II | $425M USD | Series B | United States | AI/ML, Supply Chain +3 |
| Base10 Advancement Fund IV | $425M USD | Seed | United States | AI/ML, Supply Chain +3 |
| Redbud VC Fund II | $25M USD | Pre Seed | United States | SaaS, AI/ML +3 |
| Tacora Capital Management Fund II | $685M USD | Growth | United States | InsurTech, PropTech +1 |