
Forbion Raises €2.3B Across Two New Biotech Funds
TL;DR
Forbion, the Netherlands-based life sciences venture firm with roughly €7.5 billion ($8.2B) under management, has closed €2.3 billion (about $2.6 billion) combined across two new vehicles: Forbion Growth Opportunities Fund IV and Forbion Ventures Fund VIII. The capital will back roughly 30 biotech companies spanning company creation (Ventures) and later-stage financings (Growth), with backing from Eli Lilly, Dutch pension advisor MN, PGGM, KfW Capital and the Kauffman Foundation. It lands at a moment when biotech VC fundraising has been broadly described as capital-starved, which is exactly what makes an oversubscribed €2.3 billion raise worth paying attention to.
Key Takeaways
Raising more in a down market is the real story here, not the headline number. Multiple outlets framed this raise as Forbion "bucking" the broader VC fundraising slump in biotech. A €2.3 billion close, with Forbion's own language pointing to "a general shortage of capital" in the market, signals that LPs are consolidating around a small number of managers with long track records rather than spreading commitments thin across the sector.
The step-up versus Forbion's prior pair of funds is real but modest, not explosive. In 2024, Forbion closed Growth Opportunities III (€1.2 billion) and Ventures VII (€890 million) for a combined ~€2.09 billion. The new €2.3 billion combined close is roughly a 10% increase on that figure. That is a sensible, disciplined raise for a firm that says each fund will back around 30 companies rather than an attempt to dramatically scale check sizes or company count.
Big pharma LP participation (Eli Lilly) is doing real signaling work. Strategic LP checks from large pharma companies are a vote of confidence that goes beyond capital: they often presage future partnering, licensing, or M&A conversations for the portfolio companies these funds end up building or backing.
The dual-fund structure (Ventures + Growth Opportunities) is the actual differentiator. Pairing a company-creation vehicle with a later-stage growth vehicle lets Forbion ride its own winners from NewCo formation through to growth-stage financing without having to compete against new entrants for the follow-on round. That internal pipeline is arguably more valuable to LPs than the headline fund size.
Fund Overview
Fund Name: Forbion Growth Opportunities Fund IV and Forbion Ventures Fund VIII
Fund Size: €2.3 billion (~$2.6 billion) combined; the firm has not broken out the individual sizes of each vehicle
Stage: Ventures Fund VIII backs company creation and early/proven-team biotech; Growth Opportunities Fund IV backs later-stage biopharma
Check Size: Not disclosed
Geography: Primarily Europe and North America
Focus: Innovative biotech and therapeutics addressing high-need indications, built either from scratch (NewCo model) or around proven management teams and in-licensed assets
Key LPs: Eli Lilly and Company, MN (on behalf of Dutch pension fund clients), PGGM, KfW Capital, Kauffman Foundation, plus unnamed existing and new investors
Why This Fund Matters
Biotech venture fundraising has had a rough couple of years. Public biotech valuations have been choppy, exits have been inconsistent outside of a handful of marquee M&A deals, and plenty of LPs have pulled back from new commitments to the sector in favor of safer, larger, more liquid asset classes. Against that backdrop, a €2.3 billion oversubscribed close for a life sciences specialist is a meaningful data point, not just a vanity number.
What it suggests is a flight to quality. LPs who are still willing to write checks into biotech venture appear to be concentrating around managers with two decades of history, demonstrable exits, and a repeatable playbook, rather than spreading commitments across a long tail of emerging managers. Forbion's own framing, that the raise gives it "significant dry powder" in a capital-starved market, is really a statement about competitive dynamics: less capital chasing the same (or better) deal flow should mean better entry terms for the funds that do have capital to deploy.
The structure also matters for how the capital will actually get used. Ventures Fund VIII is built to create and back therapeutics companies from the ground up or around proven teams and in-licensed science, while Growth Opportunities Fund IV exists to write larger, later-stage checks into biopharma companies with de-risked clinical data. Running both strategies under one roof means Forbion can follow its own Ventures-stage winners into growth rounds without having to out-compete new entrants for access, which is a structural advantage that's hard for single-stage funds to replicate.
Lilly's participation as an LP is worth sitting with for a moment. Large pharma companies don't typically write fund LP checks casually; they do it in part to maintain a listening post into early-stage innovation and dealflow that may eventually feed their own business-development pipeline. For founders backed by this capital, having Lilly in the LP base, even indirectly, is a soft signal that the eventual exit paths (licensing, partnership, or acquisition) may be shorter than for companies without that kind of strategic LP exposure.
The Team
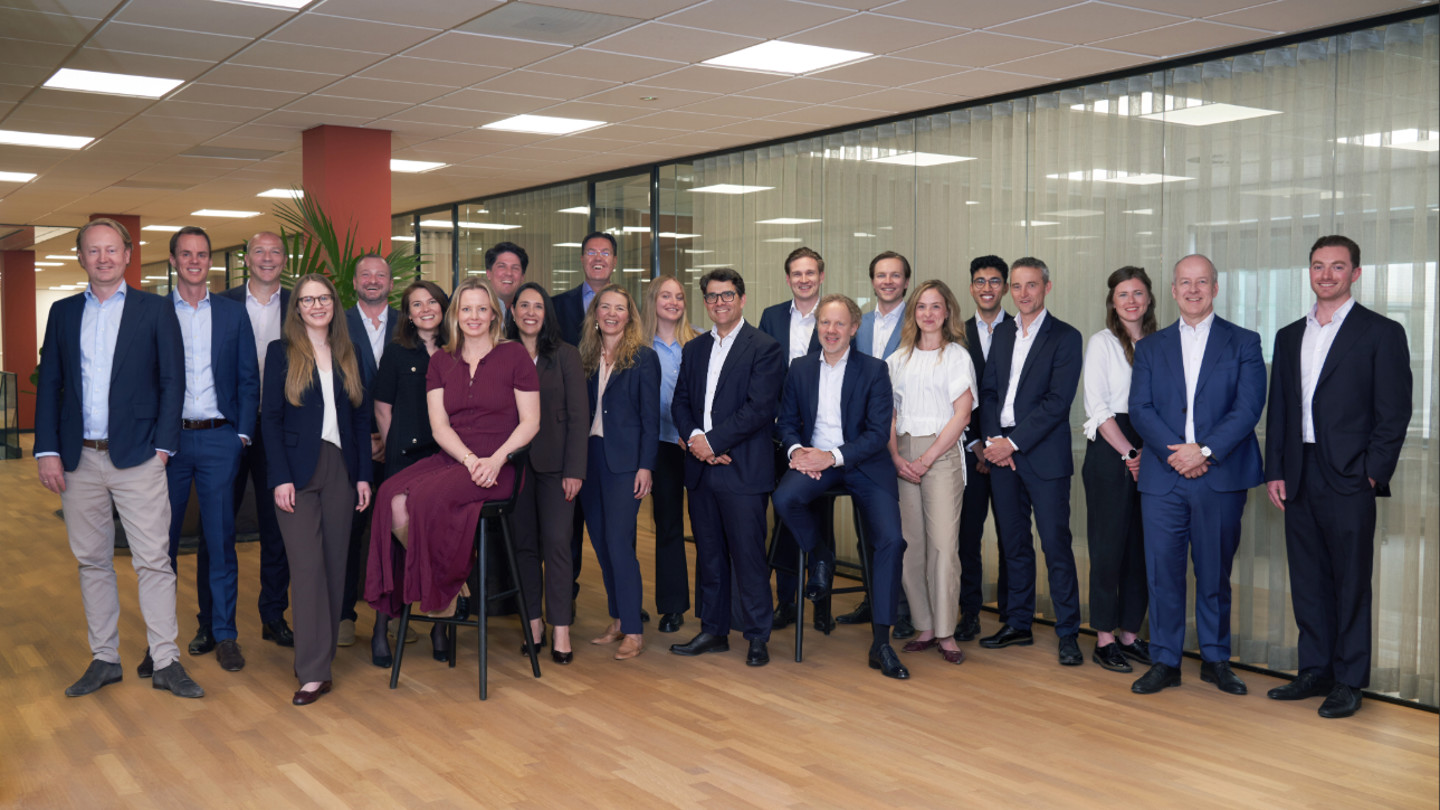
Forbion is led by Managing Partner and co-founder Sander Slootweg, who also currently chairs Invest Europe, the trade body for Europe's private equity and venture capital industry, a role that gives him an unusually wide-angle view of European fundraising conditions right now. Robbert van de Griendt, General Partner for Investor Relations and Impact, led the firm's public comments on this raise and framed the oversubscription as validation of Forbion's return history. The firm says it now runs a 35-plus person investment team out of offices in the Netherlands, Germany, and the United States, and has continued to add partner-level hires in recent years as its AUM has scaled toward €7.5 billion. We'd note, in the spirit of not overstating what we can verify, that we are not asserting a complete list of every current General Partner at the firm beyond what Forbion's own release named for this raise.
Early Portfolio
Forbion isn't disclosing which specific companies the new capital has already gone into beyond confirming that "first investments have already been made." At the firm level, Forbion points to 142 companies financed since inception (37 of which it built as NewCos from scratch), 21 approved medical products that it says have benefited more than 1.6 million patients, and more than 140 investments across 12 funds over its 20-year history. That is a track record built on volume and company creation rather than a small number of blockbuster bets, which is consistent with the dual-fund, high-conviction-but-diversified strategy described above.
What This Means for Founders
If you're building a therapeutics company in Europe or North America, especially one that could be assembled around in-licensed science or an experienced management team rather than starting from a university spin-out, Forbion's Ventures Fund VIII is now explicitly capitalized to do exactly that kind of company creation. Founders with later-stage, clinically de-risked assets looking for a growth check should look at Growth Opportunities Fund IV, which is squarely positioned for that stage.
The practical value-add beyond capital is Forbion's network into strategic pharma relationships (Lilly being the most visible example here) and its own in-house company-building capability, which matters most to founders who don't yet have a full executive team in place and are willing to let an investor help assemble one around a scientific thesis.
Fund Momentum Take
We think the headline number here is less interesting than the context around it. A ~10% step-up on the prior fund pairing sounds unremarkable until you remember that most biotech-focused managers have spent the last two years struggling to hold fund sizes flat, let alone grow them, and several well-known names have quietly downsized new vehicles. Forbion growing into a tougher market, while staying disciplined on the number of companies it plans to back per fund, is the more telling signal than the euro figure on its own.
The risk we'd flag is concentration of LP sentiment rather than concentration of capital: if biotech LPs really are consolidating around a shrinking set of "safe" managers, that's good for incumbents like Forbion in the near term but bad for the ecosystem's ability to seed the next generation of emerging life sciences managers. Founders should also note that neither fund has disclosed individual target check sizes, so expect Forbion's actual per-deal behavior, not the aggregate fund size, to be the more useful signal once allocations start showing up in cap tables.
Our bet: this raise strengthens Forbion's position as one of the two or three go-to European life sciences venture platforms for the next three to four years, and we'd expect to see it lean further into the Eli Lilly relationship for partnering-stage deal flow before this fund is fully deployed.
Frequently Asked Questions
How big is Forbion's new fund?
Forbion closed €2.3 billion (about $2.6 billion) combined across two vehicles, Growth Opportunities Fund IV and Ventures Fund VIII. The firm has not disclosed the individual size of each fund.
What stage does Forbion invest at?
Across its two new funds, Forbion covers company creation and proven-team biotech investing (Ventures Fund VIII) through later-stage, clinically de-risked biopharma growth investing (Growth Opportunities Fund IV).
Who are the limited partners in Forbion's new funds?
Named LPs include Eli Lilly and Company, Dutch pension advisor MN, PGGM, KfW Capital, and the Kauffman Foundation, alongside unnamed existing and new investors.
How does this compare to Forbion's previous funds?
Forbion's 2024 vintage, Growth Opportunities III and Ventures VII, closed at a combined roughly €2.09 billion. The new €2.3 billion combined close represents about a 10% increase.
How much capital does Forbion manage in total?
Forbion reports approximately €7.5 billion in assets under management across its history, with more than 140 investments across 12 funds.
Have a fund closing to announce? Submit your fund here.
Need help raising capital? Check out our Fundraising Advisory services.
Related funds in the index
Growth · Biotech funds from the verified index
| Fund | Size | Stage | Location | Focus |
|---|---|---|---|---|
| Forbion Fund IV | €2.3B combined (Growth Opportunities IV + Ventures VIII) EUR | Growth | Netherlands | Therapeutics, Biotech |
| a16z Growth Fund V | $8.5 billion USD | Growth | United States | AI/ML, Robotics & Automation +6 |
| Fresenius Ventures | €200M EUR | Growth | Germany | Digital Health, Therapeutics +1 |
| Anterra Capital Fund III | €86M EUR | Growth | Netherlands | AgriTech, AI/ML +2 |
| Kurma Partners Biofund IV | €215M EUR | Growth | France | Therapeutics, Biotech |