
After the Close #1: Climate VC Has a Science Project Problem
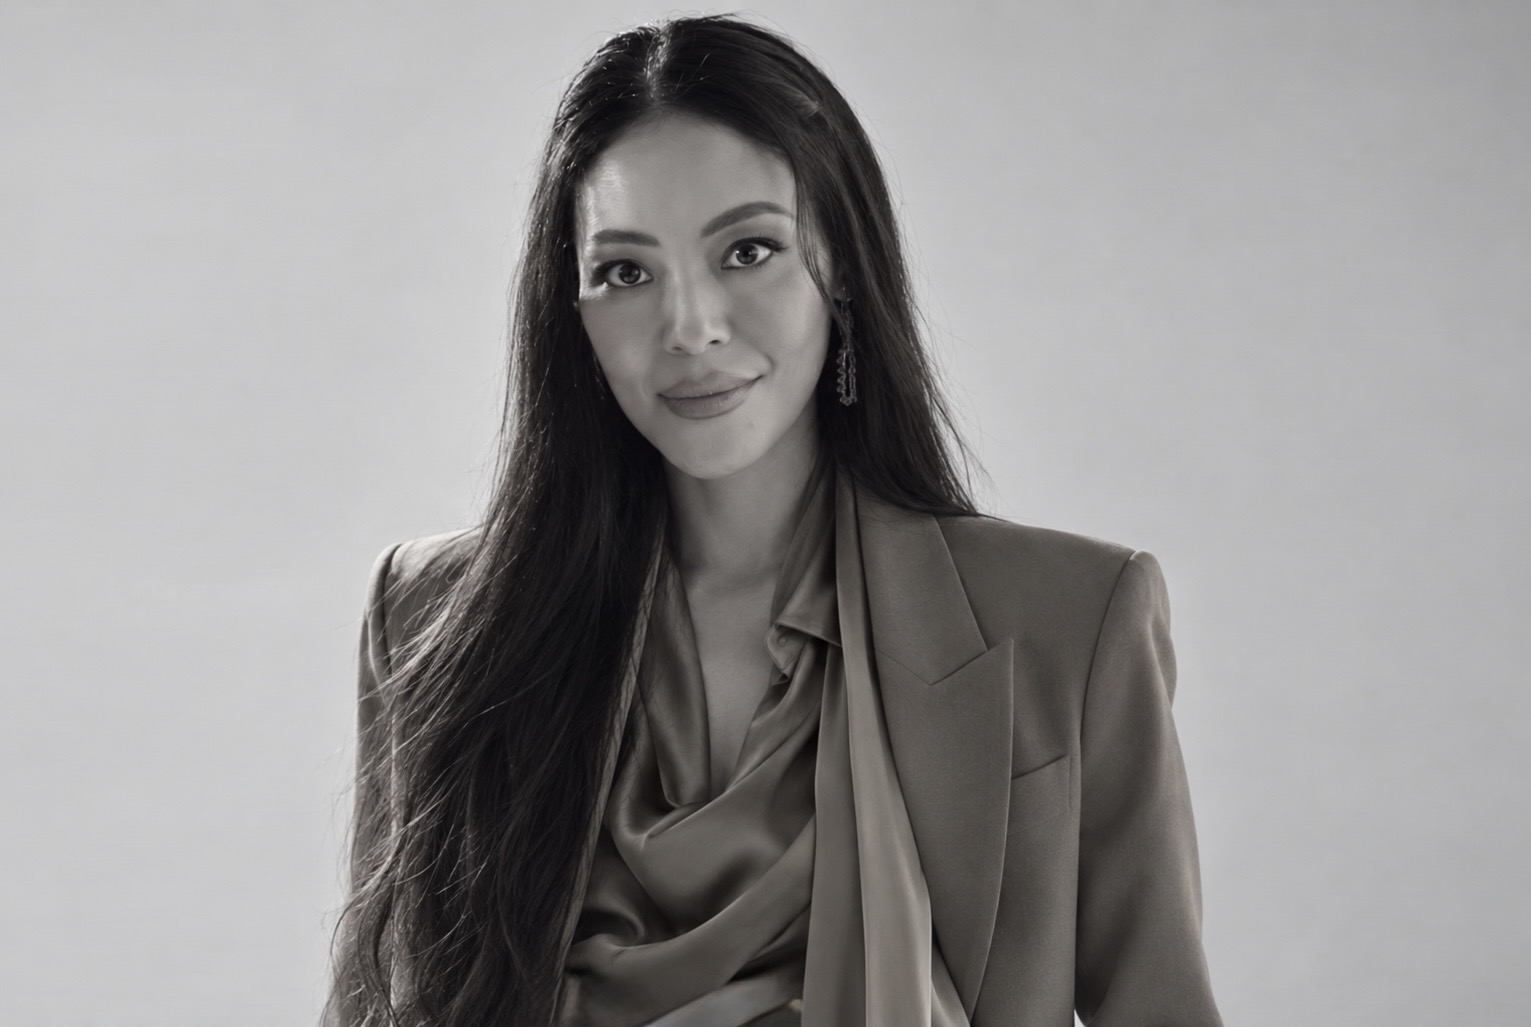
After the Close #1: Pulse Fund. Tenzin Seldon, A first-time GP on why climate capital confused ambition with viability, and the LP conversation that only closed when the numbers did the arguing.
Key takeaways for emerging managers
- Check traction before the check. Real customers paying real money is the filter, not the technology's promise.
- If your LPs see your asset class as philanthropy, no argument will move them. Show the portfolio performing instead.
- Cold outreach: lead with data, not vision. No deck in the first email, no market size in the first sentence.
Pulse Fund closed its first fund in September at $63 million. It is an early-stage climate fund that invests across software and hardware, and its disclosed portfolio includes Endera, InventWood and Twelve.
For After the Close, we talk to GPs right after a close, while the lessons are fresh and the LP war stories are still honest. Pulse is #1 because Tenzin Seldon, its Founder and Managing Partner, says things about climate capital that most fund managers only say off the record.
Q1: The origin to fund story
"It felt like the same problem showing up in every room I walked into across twenty years just wearing different texture each time."
Tenzin Seldon · Pulse Fund · After the Close #1
The line from the glacier to the fund does not feel like a line from the inside. It felt like the same problem showing up in every room I walked into across twenty years just wearing different texture each time.
I grew up in the Himalayas and when I was five a glacier above our community started melting faster than anyone remembered and the water came down and took the field where I played. In 10th grade in America in as a refugee with no network and no map for how any of it worked. Stanford and Oxford gave me a pedagogical foundation to understand social science, policy, quantitative analysis and integrative systems, which turned out to be exactly the right combination because the climate problem is simultaneously a quantitative problem and a human systems problem. The UN gave me a front row seat to watch the right policies fail because the capital refused to follow.
That last part was what broke something open for me. I was sitting in rooms where everyone understood the science, risk, and the urgency and yet, the capital didn't move. So I decided it wasn't through policies and start building companies and I kept hitting the same wall in every company I built. Not with the technology or the demand but with the capital because investors could not price companies that sat at the intersection of multiple systems since they were trained to look at one sector at a time. That experience repeated itself until I understood that the problem was not in the companies. It was upstream of them. It was in who controlled the capital and how they thought about the problem. I could keep building one company at a time or I could build the fund that changed how capital moved through the system. That conclusion kept arriving until I could not ignore it anymore.
Q2: One deal where the cross-sector thesis was the actual edge
"We are a financial fund first. Climate stabilization is the outcome we are optimizing for but returns are the mechanism that gets us there."
Tenzin Seldon · Pulse Fund · After the Close #1
We are a financial fund first. Climate stabilization is the outcome we are optimizing for but returns are the mechanism that gets us there.
At Pulse, we are early stage investors. We both lead deals and come in as follow-on investors depending on what the opportunity calls for and we have done both across the portfolio. What stays constant regardless of our position in the round is the standard we hold companies to and the unmatched value we bring after we invest. We constantly punch above our weight. Twelve's Series C is the clearest example of what leading on strategic value looks like. We co-led alongside TPG Rise Climate not because our check was the largest but because of what we see that single-vertical investors miss and what that perspective means for how a company thinks about its market and roadmap going forward. Many of the founders specifically choose to work with us, even if there are other alternative funds that are much more established.
We also made an early and deliberate decision that most climate funds were not making which is to invest across both software and hardware rather than defaulting to pure software plays because the margins are cleaner and the timelines are shorter. The energy transition is not a software problem and any fund that treats it as one is going to miss the most important companies being built right now because the electrons have to move through actual wires and the buses have to drive on actual roads and the buildings have to be constructed from actual materials and the funds that generate the best returns in this category are going to be the ones willing to underwrite hardware alongside software and understand how the two layers interact in real commercial environments.
Three companies illustrate the thesis better than one.
Endera builds electric shuttle and school buses and is the only vertically integrated American manufacturer of class four electric buses with commercial contracts already signed and revenue already flowing. Most mobility investors saw a vehicle company and most climate investors saw a fleet electrification bet and both frames were too narrow to capture what was actually interesting about it. What I saw was a company that figured out that if you own the vehicle design and the charging infrastructure and the fleet management software simultaneously you can respond to what customers actually need with a speed and precision that is impossible when you depend on three separate vendors who are not coordinating with each other. The vertical integration across hardware and software was not a feature. It was the structural reason the unit economics worked and the reason the total cost of ownership was competitive with fossil fuel alternatives in a way that pure vehicle plays or pure software plays could not replicate on their own. Single-vertical investors saw a bus company. We saw a company that had solved the infrastructure-mobility integration problem stalling fleet electrification everywhere else and had the commercial traction to prove it was not a science project.
It's electric builds curbside EV charging infrastructure specifically designed for cities and the insight nobody was pricing correctly was that the barrier to urban EV adoption was not the vehicles or the chargers in an abstract sense but the physical infrastructure underneath the chargers that made installation prohibitively expensive and slow in dense urban environments. It's electric solved that by partnering with building owners to tap into untapped electricity already inside urban buildings and sharing the revenue with them which simultaneously solves the installation cost problem and creates a recurring revenue stream for property owners who have no other way to monetize that electrical capacity. That is simultaneously an energy play and a real estate play and an infrastructure play and a mobility play and the reason most investors could not see all four dimensions at once is that they were trained to look at one of them at a time and we kept saying that question misses the point because the value of the company comes precisely from the fact that it sits at the intersection of all four.
InventWood developed MettleWood which is a wood-based structural material 60% stronger than construction grade steel but eighty percent lighter and dramatically more sustainable and they recently received a 20M dollar SCALEUP award from ARPA-E on top of funding from the Grantham Foundation and Builders Vision. On the surface it looks like a materials company and if you only have one frame that is what you see. But the cross-sector insight that drove our conviction was that InventWood is not primarily a materials company but a building decarbonization company that simultaneously solves the construction industry's carbon emissions problem and the carbon storage problem in the same product because buildings constructed with MettleWood actively store carbon in the structure itself for the life of the building. Buildings account for roughly forty percent of global carbon emissions and InventWood replaces steel and concrete simultaneously while flipping the carbon accounting from a liability to an asset and they have eleven awarded patents and over a hundred pending and a ninety thousand square foot production facility already manufacturing at scale.
The consistent pattern across all three is that we get access before companies are legible to single-vertical funds because we understand what they are before the market has vocabulary to describe them accurately and by the time the market catches up and the category becomes crowded the price is already competitive and the best positions are already taken. We find them while the market is still misreading them and when we get in whether we are leading or following we bring a perspective on how the systems they operate across connect and compound that shapes how founders think about their roadmap in ways that go beyond what the check itself provides. That is why founders want us in the round regardless of our position in it. Not just because of the check. Because of what the check comes with.
Q3: What is currently wrong about how climate capital is deployed
"the job of a venture fund is not to fund science but to fund companies"
Tenzin Seldon · Pulse Fund · After the Close #1
Early on, a lot of climate capital was chasing science projects disguised as investment theses and not enough were backing companies with real commercial traction that the category has spent too long blurring that distinction in ways that have cost LPs real money and damaged the credibility of the entire asset class.
What I see constantly is early stage venture capital funds backing companies with pioneering technology and a 10 year timeline to meaningful revenue and calling that a climate investment. Maybe the science is real and the technology will work but that is simultaneously a bet that the science works and the market develops and the regulatory environment cooperates and the team stays funded through all of it and those are four separate bets stacked on top of each other that most of them do not all resolve in your favor across a fund lifecycle. The 2021 peak and the subsequent crash in climate valuations was in significant part the result of capital that had confused scientific ambition with commercial viability and the LPs who got burned in that cycle have not forgotten it which is part of why raising climate funds has been so hard for the last three years.
What we look for is different and we hold this standard even at the earliest stages we invest at. We want to see evidence that the commercial model is working before we write the check. Real customers paying real money for a real product or a credible and near-term path to that outcome that does not require six things to go right simultaneously. That standard filters out a significant portion of what gets called climate investing right now and I think that filtering is exactly right because the job of a venture fund is not to fund science but to fund companies and there is a meaningful difference between those two things that the climate category has been too slow to internalize.
The other thing I think is wrong is the default toward pure software plays because the margins are cleaner and the diligence is more familiar. The energy transition is a physical world problem and the funds that generate the best returns over the next decade are going to be the ones willing to underwrite hardware alongside software and understand how the two layers interact in real commercial environments and that requires a different kind of expertise and tolerance for complexity than most climate funds have been willing to develop.
Q4: The LP conversation that almost did not work
"We were not just making the case for Pulse Fund. We were making the case that climate investing is investing at all and not just philanthropy with better branding."
Tenzin Seldon · Pulse Fund · After the Close #1
A significant number of the investors we talked to had never invested in climate as a financial opportunity before. They had viewed climate as a philanthropic cause. They had written checks to foundations and conservation organizations and policy advocacy groups and they thought of climate capital through that lens as money you give away because it is the right thing to do rather than money you deploy because it generates returns. That mental model was the hardest thing to shift and it required a different kind of conversation than a typical fund pitch because we were not just making the case for Pulse Fund. We were making the case that climate investing is investing at all and not just philanthropy with better branding.
The education piece was real and it took time. We had to sit with people and walk them through the data. Climate tech VC outperforming broader venture by 9% IRR in the 2020 to 2024 vintage according to Silicon Valley Bank. The portfolio companies generating real revenue with institutional co-investors like TPG and Munich Re and Goldman Sachs validating the commercial model independently of anything we said about it. We had to show them what the numbers actually looked like and then let the numbers do the work rather than asking them to take the thesis on faith.
The specific conversation that almost did not work had that philanthropic starting point underneath it. The objection that kept coming back was not articulated as we do not think climate generates returns because nobody wants to say that out loud. It was articulated as a series of diligence questions that kept coming back to the same underlying concern which was whether a climate fund run by a first-time manager with no prior venture fund track record could actually perform like a real investment rather than a well-intentioned one. Every time we answered the last question, a new version of the same concern would surface and I understood eventually that we were not answering a diligence question. We were trying to shift a frame about what climate capital actually is.
What finally moved it was not a new argument but a different kind of demonstration. We stopped explaining the thesis and started showing the portfolio companies performing in real time with real co-investors and real commercial contracts and real revenue and we let the evidence answer the question that the conversation kept circling around. The shift from philanthropy to investment did not happen because we made a compelling argument. It happened because the numbers made an argument that was harder to dismiss than any we could have constructed ourselves.
I do not know if that was the moment the conversation turned. What I know is that it did not end that day and it did not end the next time either and eventually it closed. And what I took from it was that the hardest LP conversations in climate investing are not the ones where people think you cannot perform. They are the ones where people have never been asked to think of climate as performance at all. Shifting that frame is slower and harder than any other part of the fundraise and it is the work that does not show up in the pitch deck but determines whether the pitch lands.
Q5: A deal you talked yourself out of or are not sure about
"There is a version of that decision that is disciplined and correct and there is a version of it that is just the kind of risk aversion that keeps emerging managers from backing the companies that would define their funds"
Tenzin Seldon · Pulse Fund · After the Close #1
There is a company I passed on that I think about more than I should and what makes it interesting is that it was not an impact play at all which is part of what made it hard to evaluate against the Pulse thesis.
It was a commercial company that looked at forestry and ag tech in South Asia. Purely commercial with strong unit economics and real revenue and real customers and none of the science project risk that I spend a lot of time filtering out in climate investing. The founders were strong and the market timing felt right and the business itself was working in ways that most early stage companies are not and on the commercial metrics alone it was one of the cleaner opportunities I looked at that year.
The problem was the risk profile and I could not get around it no matter how many times I came back to the model. The geographic complexity was real and the regulatory environment in that market was moving in ways that were difficult to predict and the capital requirements to scale in that context were larger than what I could commit to from our fund that made sense for the portfolio construction. It was not that I did not believe in the company because I did. It was that the combination of geographic risk and capital intensity and regulatory uncertainty stacked on top of each other in a way that I could not fully underwrite from where I was sitting at that stage of the fund.
What I kept coming back to after I passed was whether I had made a risk management decision. There is a version of that decision that is disciplined and correct and there is a version of it that is just the kind of risk aversion that keeps emerging managers from backing the companies that would define their funds and I do not know with confidence which version I made in that moment. What I do know is that the company continued to perform after I passed and that performance has made the question harder to dismiss than it would have been if the opposite had happened.
The honest answer to how I tell the difference between a disciplined no and a mistaken no in real time is that geographic and regulatory risk are the hardest categories of risk to evaluate clearly because they require a depth of local knowledge that is very difficult to acquire from the outside and very easy to underestimate from the inside of a model and that asymmetry is something I am still learning to navigate more honestly than I did in that moment.
Q6: How founders should reach out and what the red flags are
"If you are going to cold email lead with the data not the vision. We can evaluate vision later."
Tenzin Seldon · Pulse Fund · After the Close #1
Warm introductions from someone we trust move fastest and that is just the honest truth of how early stage investing works. Cold emails are rare for us but they do work occasionally and when they do it is because the founder led with the numbers and the commercial traction and made the fit to our thesis immediately clear in the first paragraph. If you are going to cold email lead with the data not the vision. We can evaluate vision later. What gets our attention first is evidence that the commercial model is already working.
The red flags are consistent. A deck in the first email. A market size claim in the first sentence. Competitive landscape analysis before we have even had a conversation. All of those things tell me the founder has been coached on what VCs want to see rather than thinking clearly about what the purpose of a first message actually is which is simply to make us want to have a conversation. Send the deck after we talk not before.
The thing that makes me stop reading immediately is when I cannot feel the founder in the message. The founders we back have a specific point of view that comes through even in a cold email and that specificity is what I am looking for because a generic message cannot answer the only question that actually matters which is whether this is the person who has to build this particular thing at this particular moment.
About Pulse Fund and Tenzin Seldon
Pulse Fund is a $63 million early-stage climate fund based in Los Angeles, investing across energy, food and agriculture, infrastructure and mobility. Tenzin Seldon, a Himalayan climate investor, is its Founder and Managing Partner. She studied at Stanford and Oxford and worked at the UN before building climate companies and starting Pulse.
Meet Pulse's LPs
Publicly disclosed backers of Pulse Fund I, each with a profile on Fund Momentum: Beneficient, C6 Partners, Pivotal Foundation, the Pritzker family, Veronica Chou and David Osborn, plus an Asia-based sovereign wealth fund that has not been named.
Raising your own fund?
LP Radar shows which LPs are actively backing emerging managers, so you can see who writes first-time-fund checks before you start outreach.
Have a fund closing to announce? Submit your fund here.
Related funds in the index
Climate & Sustainability funds from the verified index
| Fund | Size | Stage | Location | Focus |
|---|---|---|---|---|
| Oraseya Capital Fund | AED 1B AED | Pre Seed | United Arab Emirates | Digital Education (Consumer), Climate & Sustainability +5 |
| Graduate Ventures Seed Fund II | €125 million target EUR | Pre Seed | Netherlands | Digital Health, Climate & Sustainability +2 |
| WEH Ventures Fund III | ₹250 crore target INR | Pre Seed | India | Digital Health, AI/ML +6 |
| Eureka! Fund II – Deep Tech Lazio | €20M EUR | Pre Seed | Italy | Defense, Mobility & Transport +6 |
| Bramble Partners Fund I | Targeting £100 million GBP | Series A | United Kingdom | Circular Economy, Climate & Sustainability |